
Perspectives
China’s Factory Profits Jump Early in 2026, but Energy Shock Clouds the Outlook
China’s industrial firms reported a strong start to the year, with profits rising sharply in the first two months as factory activity picked up and pricing improved in parts of the economy. The rebound offers policymakers a welcome data point after years of uneven recovery, but it is landing against a new risk: higher global energy prices that could squeeze margins and weaken demand if they persist.
Official data showed industrial profits climbed 15.2% year over year in the January to February period, extending momentum from a smaller gain recorded late last year. Government statisticians pointed to faster production and firmer product prices as key drivers of the improvement, suggesting that some manufacturers are seeing better operating conditions than they did through much of the past year.
High-tech leads, commodities follow
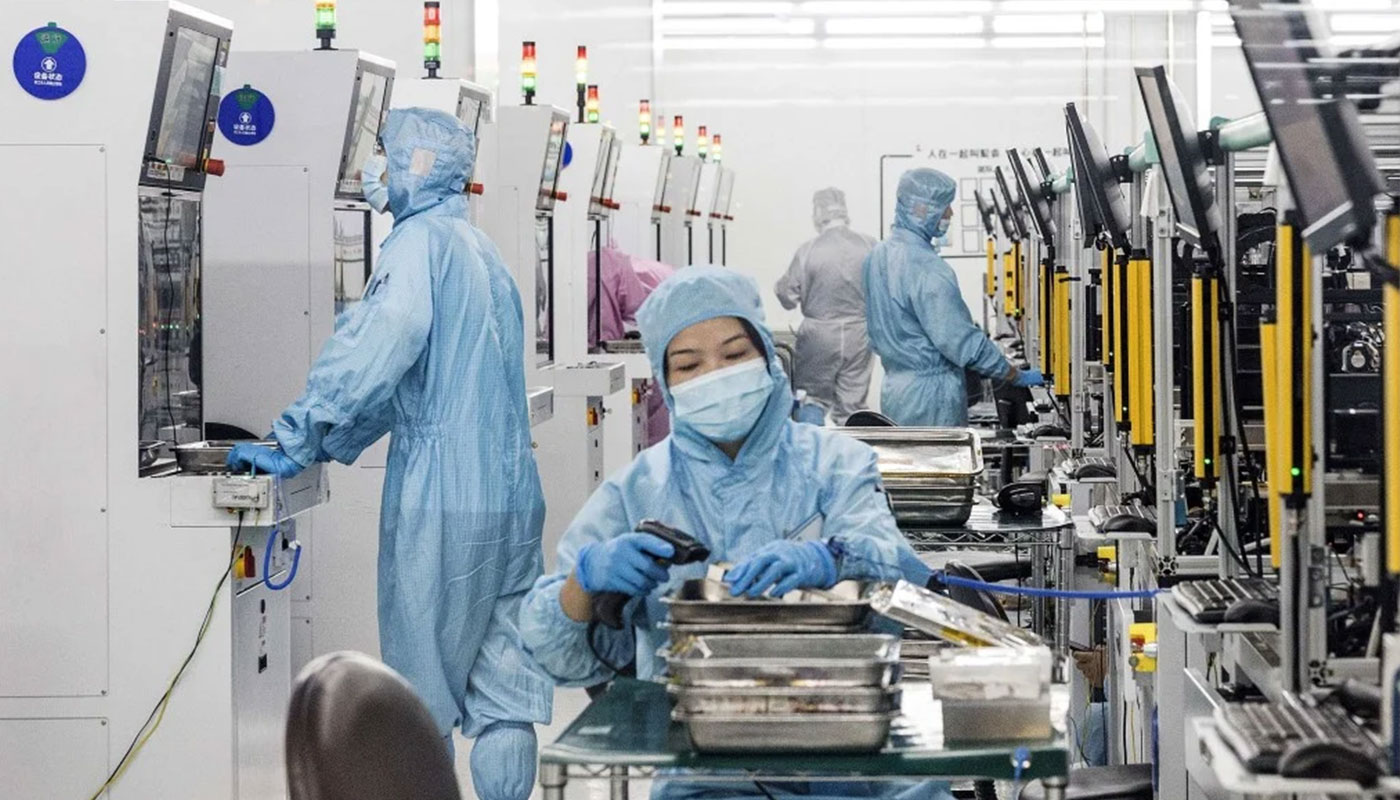
The strongest profit gains came from high-tech manufacturing, where earnings jumped 58.7% year over year. Officials highlighted particularly strong results among companies tied to unmanned aerial vehicles and semiconductors, sectors that have benefited from policy support, export demand, and continued investment in domestic supply chains.
Commodity-linked industries also posted outsized increases. Producers of non-ferrous metals reported a large rise in profits, while parts of the chemicals sector also recorded strong growth. These categories tend to benefit when upstream pricing improves, and when industrial demand stabilizes enough to reduce the worst of the price competition that has weighed on margins in recent years.
The recovery remains uneven
Even with the headline jump, officials cautioned that the improvement is not uniform across the economy. China is still dealing with a familiar set of constraints: excess industrial capacity in some sectors, cautious consumer spending, and patchy confidence among private firms.
For all of 2025, industrial profits rose only modestly, ending a multi-year period of declines. That stabilization was helped by efforts to curb the most aggressive price wars in certain industries and by companies leaning more heavily on export markets to offset soft domestic demand. The early-2026 rebound suggests conditions have improved further, but the durability of the trend will depend on whether demand holds up and whether costs stay manageable.
Energy prices are the key new threat
The biggest near-term variable is energy. Global oil prices have surged following disruptions linked to the Middle East conflict, and China is already taking steps to prevent a rapid pass-through into household and business costs.
Authorities recently raised retail ceiling prices for gasoline and diesel but capped the increase at roughly half the usual adjustment, aiming to soften the impact on consumers. That kind of intervention can help in the short run, but it also means energy price pressure may show up elsewhere, including in corporate margins, logistics costs, and fiscal burdens if support measures are expanded.
China is better insulated than many economies because it has large reserves and a broad set of alternative energy sources. In addition, crude flows from Iran have continued, helping to cushion supply risks. Still, if oil stays high for an extended period, it could weigh on an economy that remains sensitive to cost shocks, especially at a time when consumer demand is not fully robust.
What to watch next
The profit rebound is real, but it is also vulnerable. Three factors will likely determine whether the early-year strength persists:
- Energy costs: how much higher oil prices feed into input costs and transportation, and how much pricing power firms have to pass them on.
- Domestic demand: whether consumption improves enough to support volumes without renewed discounting.
- Policy response: whether officials expand support measures to cushion households and industry, and how that affects longer-term financial stability.
For now, China’s industrial sector is showing early momentum. The question is whether firms can hold on to it if the energy shock deepens and the external environment becomes more volatile.